Insurance has become one of the biggest swing factors in Florida real estate deals. A few years ago, most investors treated it as a line item they plugged in near the end of underwriting. Today, it can decide whether a rental cash flows, whether a flip still pencils, or whether a loan closes on time.
If you invest in Florida, you can't afford to guess on insurance anymore. Here's what's driving costs, how they affect your numbers, and what smart investors are doing about it.
Why Florida insurance got so expensive
Florida premiums climbed for years because of a mix of storm risk, lawsuits, and a shrinking pool of carriers.
- Hurricane exposure. Florida carries more coastal storm risk than almost any state. Major storms drive up claims and the cost of reinsurance, which insurers pass on to policyholders.
- Litigation. Before reforms in 2022 and 2023, one-way attorney fees and assignment-of-benefits abuse fueled a wave of lawsuits. That drove up claim costs for everyone. (Florida CFO)
- Carrier exits. Several insurers left the state or went insolvent. Fewer options meant less competition and higher prices.
- The state insurer of last resort grew. Citizens Property Insurance peaked at about 1.4 million policies in September 2023, holding roughly 15% of the market. (Florida Trend)
For investors, this showed up as bigger renewal increases, harder-to-place policies on older homes, and more time spent shopping for coverage before closing.
How insurance changes your deal math
Insurance is part of your monthly housing payment, so every increase cuts straight into cash flow and debt service coverage.
Here's a simple example on a single-family rental. These are hypothetical numbers for illustration, not data from a real property:
|
Lower premium |
Higher premium |
| Monthly rent |
$2,400 |
$2,400 |
| Principal & interest |
$1,500 |
$1,500 |
| Property taxes |
$400 |
$400 |
| Insurance |
$200 ($2,400/yr) |
$500 ($6,000/yr) |
| Total monthly payment |
$2,100 |
$2,400 |
| DSCR |
1.14 |
1.00 |
Hypothetical example for illustration only.
Same house, same rent, same loan. A $3,600 jump in the annual premium takes the property from positive cash flow to break-even, and it can change which loan terms you qualify for.
Insurance also affects:
- Cash to close. You usually prepay the first year's premium at closing.
- Property value. Higher carrying costs lower what buyers can pay, which can pressure cap rates and resale prices.
- Timelines. A policy that's hard to bind can delay a closing.
What it means for each investment strategy
- Fix & flip. You'll need builder's risk or vacant-property coverage during the rehab, which often costs more than a standard policy. When you sell, your buyer's insurance quote can make or break their offer, so updates like a new roof or impact windows add real resale value.
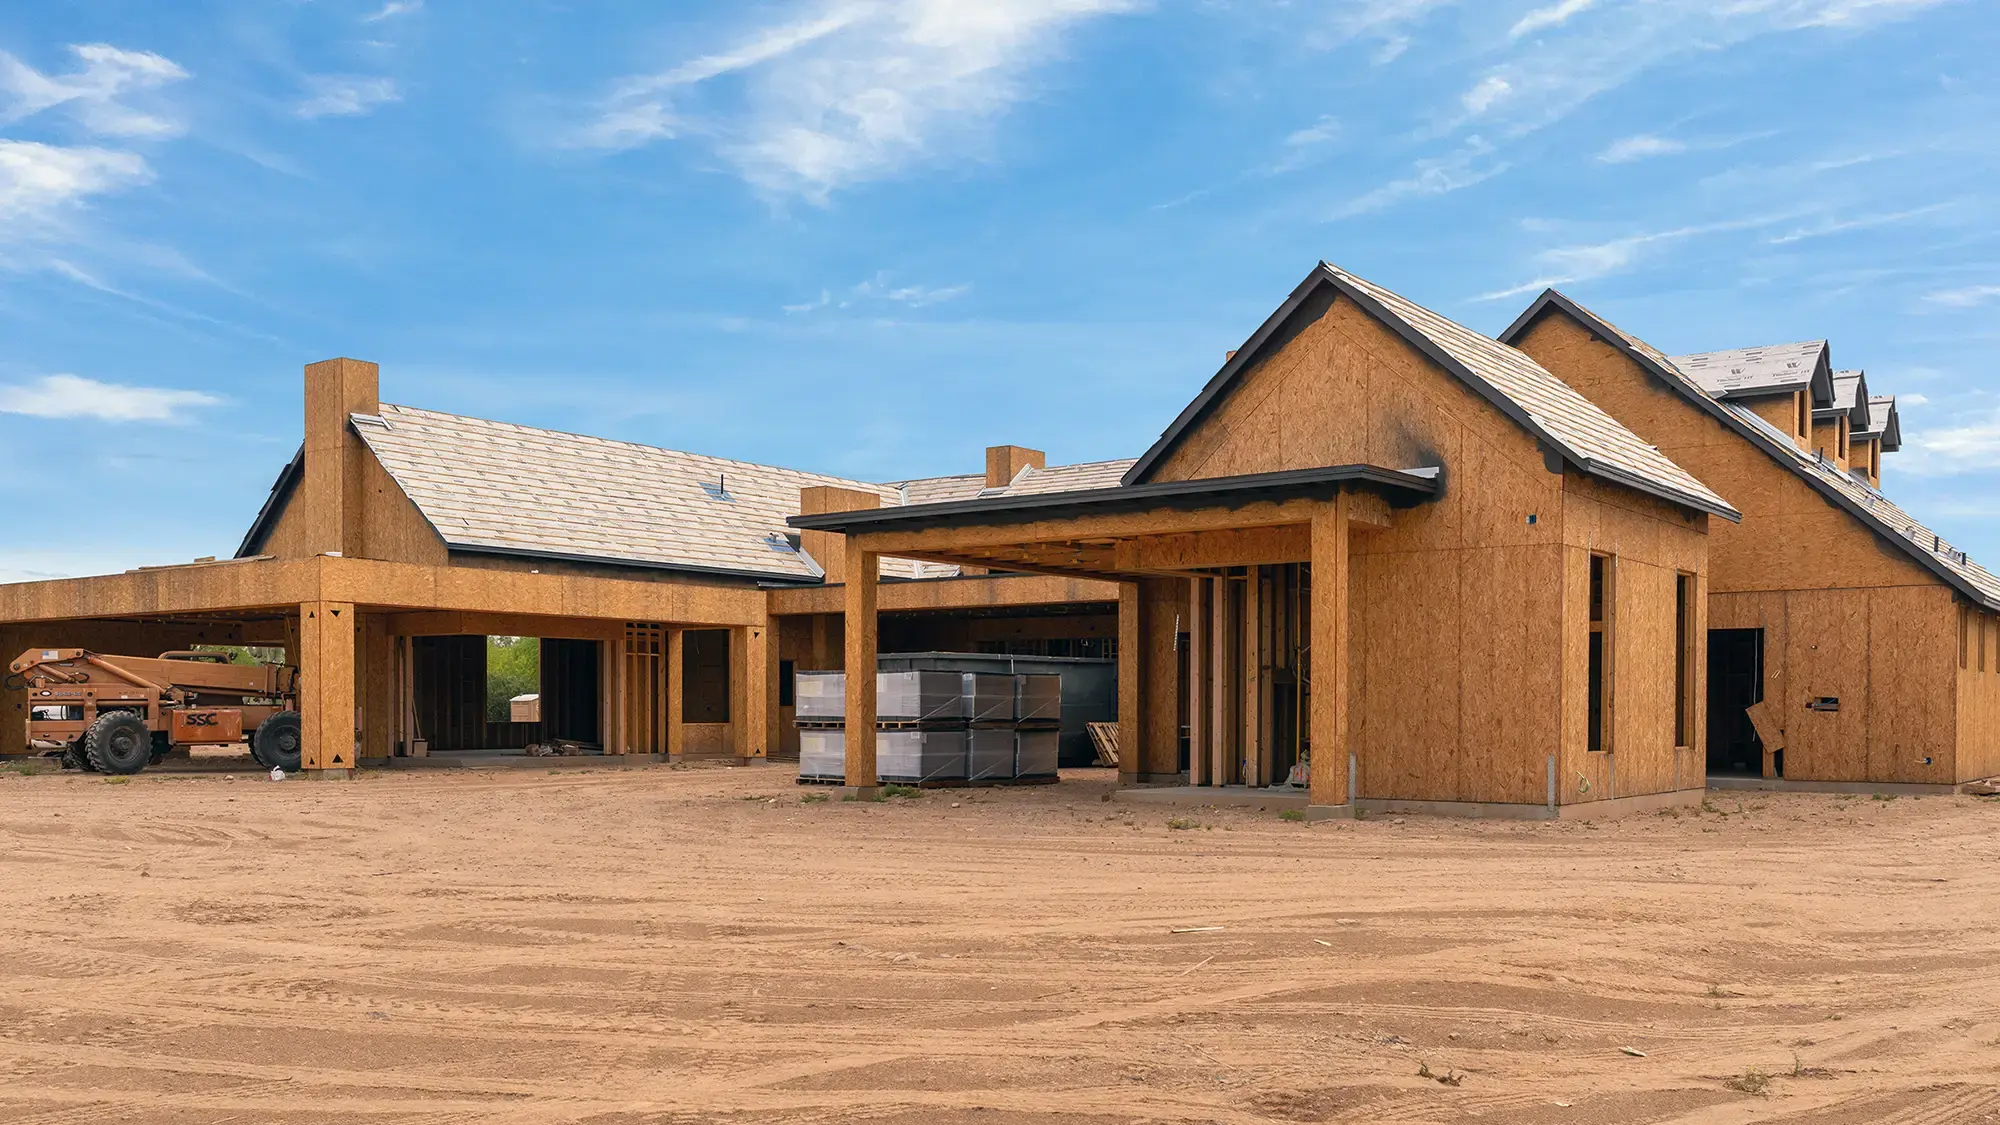
- Ground-up construction. Builder's risk premiums depend on location, construction type, and timeline. New builds that meet current Florida Building Code standards usually insure for less once complete, which is a selling point for buyers and renters.
- Bridge loans. If you're buying to reposition, budget for the insurance you'll pay during the hold, not just after stabilization.
- DSCR rentals. Insurance is part of the payment your rent has to cover. A higher premium lowers your DSCR, so get a real quote before you lock in a purchase price.
How smart investors are adapting
- Get quotes before you make an offer. Don't wait until you're under contract. A quick quote tells you if the deal still works.
- Check the roof's age and condition. Older roofs are one of the biggest reasons for high premiums or declined coverage in Florida.
- Order a wind mitigation inspection. Features like hurricane straps, impact windows, and roof-to-wall connections can earn meaningful discounts.
- Look up the flood zone. Standard policies don't cover flood. Know whether flood insurance is required, and what it costs, up front.
- Underwrite with a cushion. Build in room for renewal increases so one bad year doesn't wipe out your margin.
- Shop every renewal. With more carriers back in the market, comparing quotes at renewal can pay off.
- Factor in upgrades. A new roof or impact windows can lower premiums and raise resale value at the same time.
The good news: the market is starting to stabilize
After years of increases, Florida's insurance market is showing real signs of relief in 2026.
- Rates are coming down in most counties. State data shows average premiums fell in 51 of Florida's 67 counties between January and July 2026. In Palm Beach County, the average dropped from $6,412 to $6,323. (WPTV)
- More carriers are competing. 17 new insurance companies have entered Florida since the reforms, according to the state. (Florida CFO)
- Citizens is shrinking. Citizens dropped from 1.4 million policies in 2023 to about 255,000 by September 2026, roughly 1.8% of the market. (Florida Trend) Its average rates fell 8.7% statewide, with reductions around 14% in Miami-Dade and Broward. (Florida CFO)
- More cuts may be ahead. Florida's insurance commissioner expects more rate decreases into 2027, with requested changes ranging from -0.3% to -19.7%. (Florida Trend)
That said, premiums are still high compared to most states, and one major hurricane could shift the picture quickly. The takeaway: costs are easing, but insurance still belongs at the top of your underwriting checklist.
The bottom line
Insurance is no longer an afterthought in Florida real estate. It shapes cash flow, loan qualification, and resale value. Investors who quote early, underwrite carefully, and invest in upgrades that lower risk will be best positioned as the market keeps shifting.
At Lendyx, we help investors finance Fix & Flip, Ground-Up Construction, Bridge, and DSCR rental deals across Florida. If you're running the numbers on your next project, email us at deals@lendyx.com and we'll help you structure a loan that fits your deal.