A traditional construction loan is built for larger, slower projects with long approval timelines. An infill construction loan is built for small urban lots, tight timelines and repeat investors who need to move fast. If you build on infill sites, the right loan type can decide whether you win the lot at all.
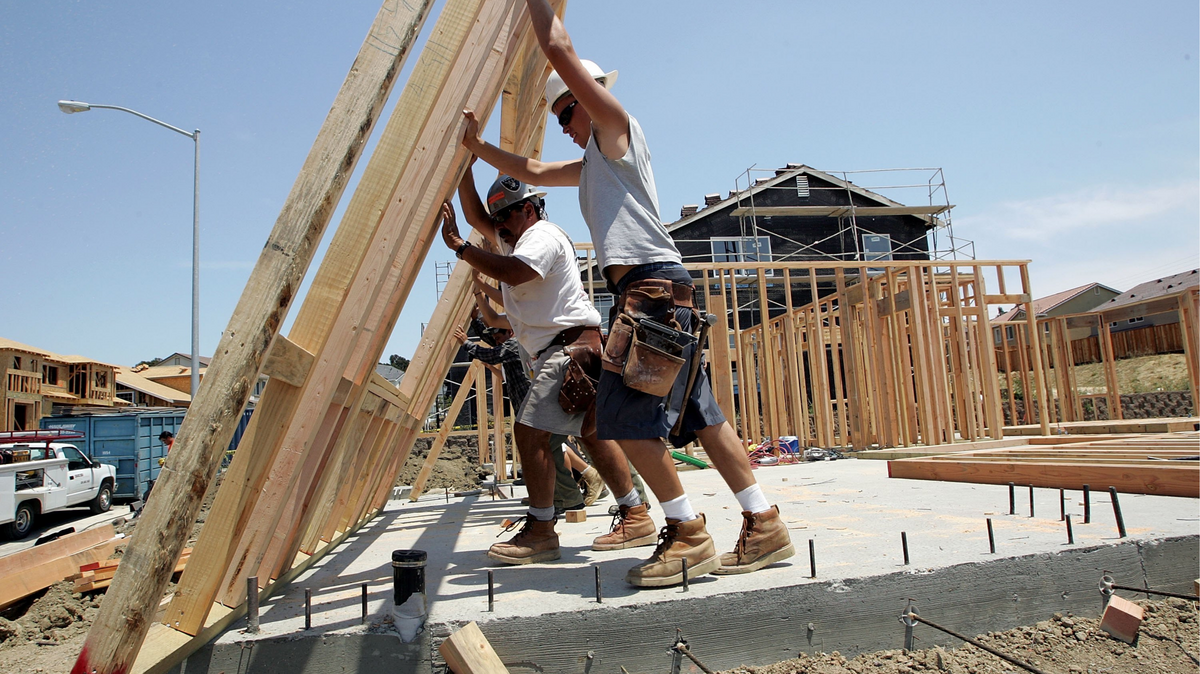
Traditional construction loans fund ground-up building, usually on larger or greenfield sites. They often come with long approvals, heavy paperwork and strict borrower requirements.
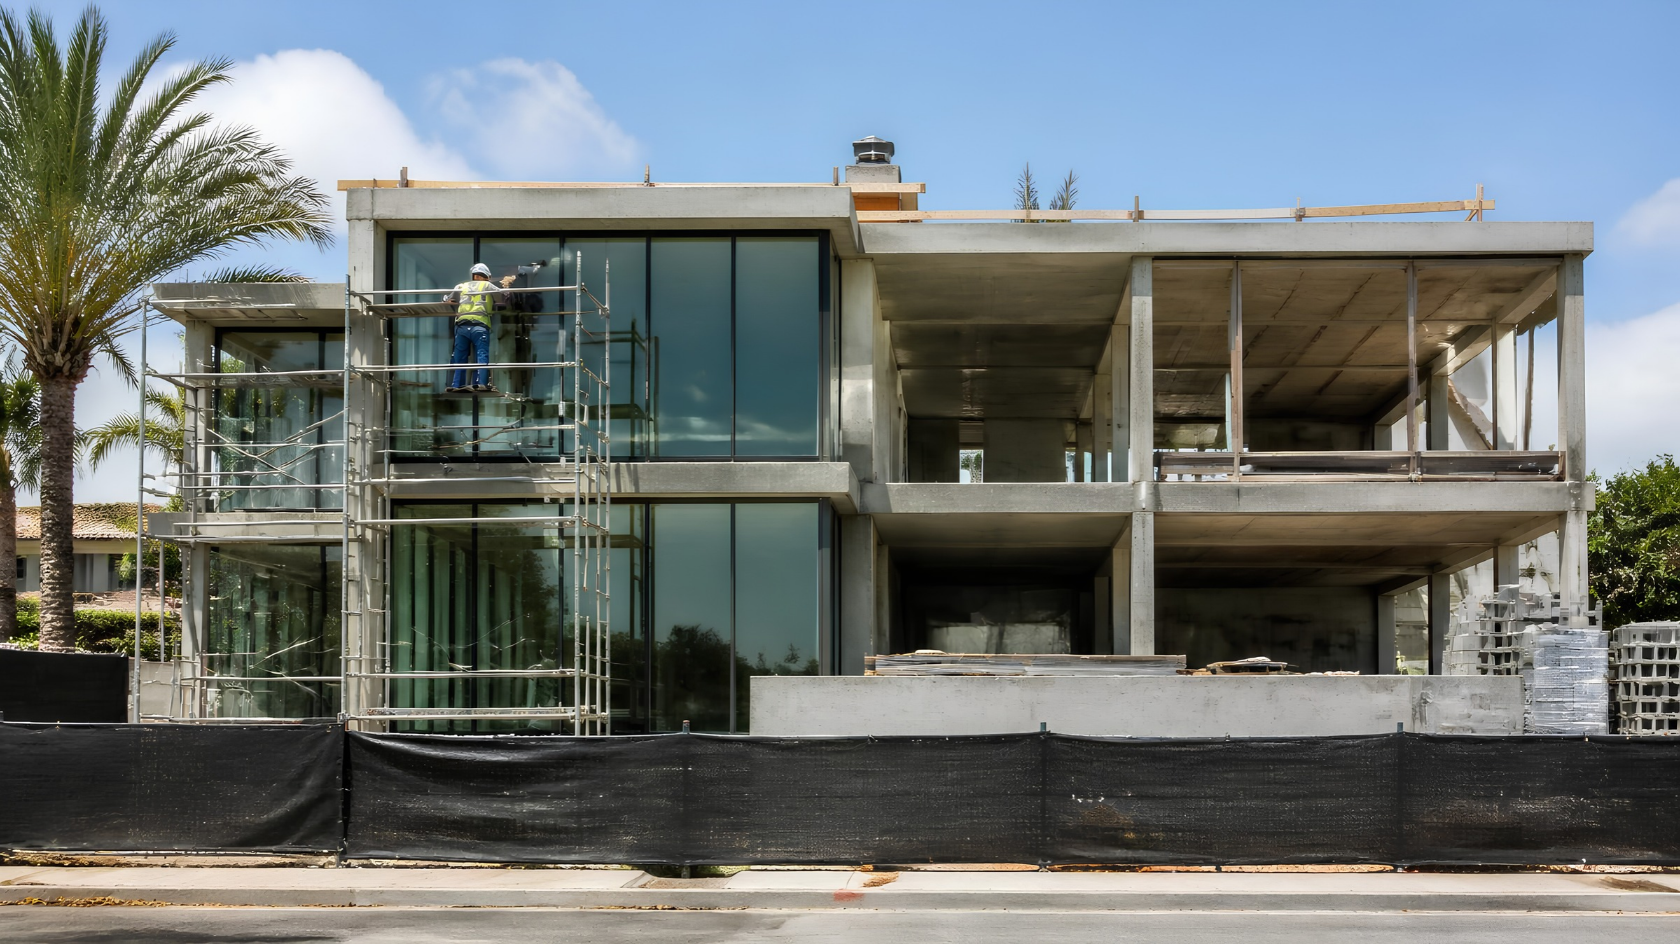
Infill construction loans fund building on vacant or teardown lots inside established neighborhoods: single-family homes, townhomes, ADUs, small multifamily and build-to-rent communities. They are designed around speed and the realities of urban sites.
For most repeat infill investors, the sweet spot is a direct private lender: one that underwrites, approves and funds in-house, rather than a broker passing your file along. Fewer hands means fewer delays and fewer last-minute changes to terms.
Three things decide whether a construction loan helps or hurts your project.
1. Speed. Look for terms in days and a close in weeks. On infill lots, sellers favor buyers who can close fast. Slow approvals can cost you the site before you ever break ground.
2. Project fit. Your financing should fit your deal type: small lots, ADUs, townhomes, build-to-rent communities. Infill sites need a lending team that knows how to value a tight urban lot.
3. Execution certainty. The terms you sign should be the terms you close on, and draws should arrive on schedule. Construction loans live and die on draws. A late draw stalls your crew, pushes your timeline and eats your margin.
Know upfront how long a typical draw takes from request to funding, and who approves it.
Lendyx is a direct real estate lender based in Miami. Our Ground-Up Construction loans are built for infill investors who need fast terms, a lending team that understands urban sites, and draws that keep crews working.
Have a site in mind? Submit your project at deals@lendyx.com.

Apply in minutes. Close your loan quickly.